
Seven Key Charts on the State of the Australian Property Market

The Australian residential property market creates much consternation. On one level there is the debate about the outlook for home prices with some real estate spruikers still wheeling out versions of the old “property will double every seven years” line versus property doomsters at the other extreme saying it’s overvalued and overindebted and so a crash is inevitable.
Key points
The Australian housing market remains far more complicated than many portray it to be.
The Australian housing cycle is turning up again; falling interest rates are the key driver; along with a chronic undersupply of homes of 200,000-300,000 dwellings; this partly reflects a surge in building times; poor affordability is a key constraint though; but it varies significantly between cities; and finally, mortgage arrears remain low.
Average prices are expected to rise 5-6% this year boosted by falling rates but constrained by poor affordability.
Introduction
The Australian residential property market creates much consternation. On one level there is the debate about the outlook for home prices with some real estate spruikers still wheeling out versions of the old “property will double every seven years” line versus property doomsters at the other extreme saying it’s overvalued and overindebted and so a crash is inevitable. The problem with the former is that it implies the already high ratio of home prices to incomes will double again over 12 years. The trouble with the doomsters is that they’ve been saying that for decades. On another level there is much understandable angst about affordability with some blaming investors and property tax breaks versus others seeing it as largely due to poor housing supply relative to demand. As always with these things there is no black or white answer. To shed some light on this here are seven key charts on the state of the housing market.
First – the property cycle looks to be turning up again
After a brief dip of just 0.3%, national average property prices have been rising steadily from February indicating that they have entered a new cyclical upswing. So far, the gains have been broad based with the soft cities of Melbourne, Hobart, Canberra, Darwin and Sydney now picking up at the same time that the boom time cities of Brisbane, Adelaide and Perth remain strong.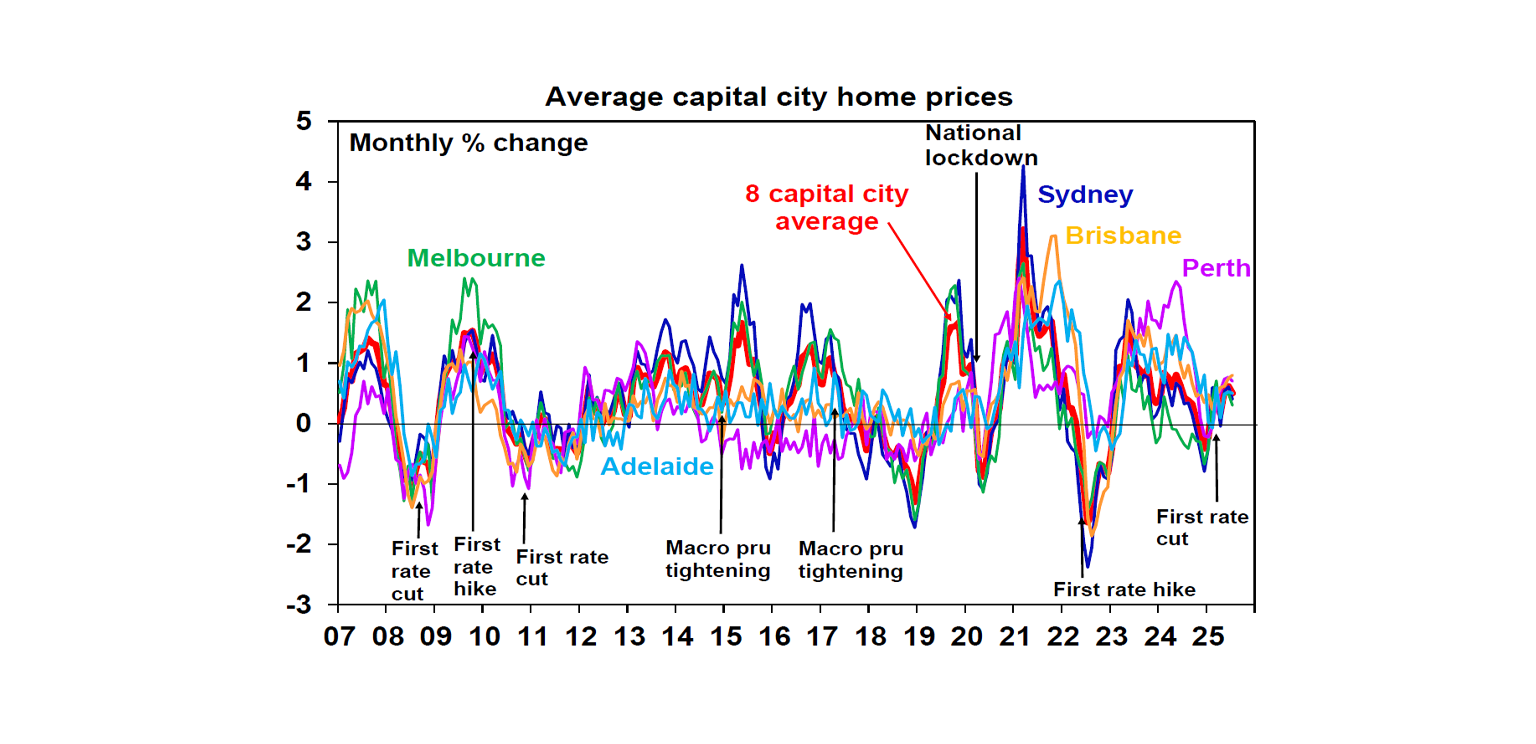 Source: Corelogic, AMP
Second – interest rates are a key driver
Interest rates matter a lot to the property market because lower rates boost the relative attractiveness of property as an investment and allow home buyers to borrow more. And vice versa for higher rates. Of course, the impact of interest rates can be swamped by other factors at times, as was the case in 2023-24 with the population surge and weak supply. Lower rates are a key driver of the current upswing in prices. Since 1982, the start of rate-cutting cycles has generally been associated with higher home prices over the next 12 and 18 months in five of the last seven cycles, provided there is no recession. The average gain over the subsequent 12 and 18 months is 3.9% and 8%. The base case is for 0.25% RBA rate cuts in August, November, February and May. With increasing signs of labour market weakness, this may occur faster with back-to-back cuts in August and September.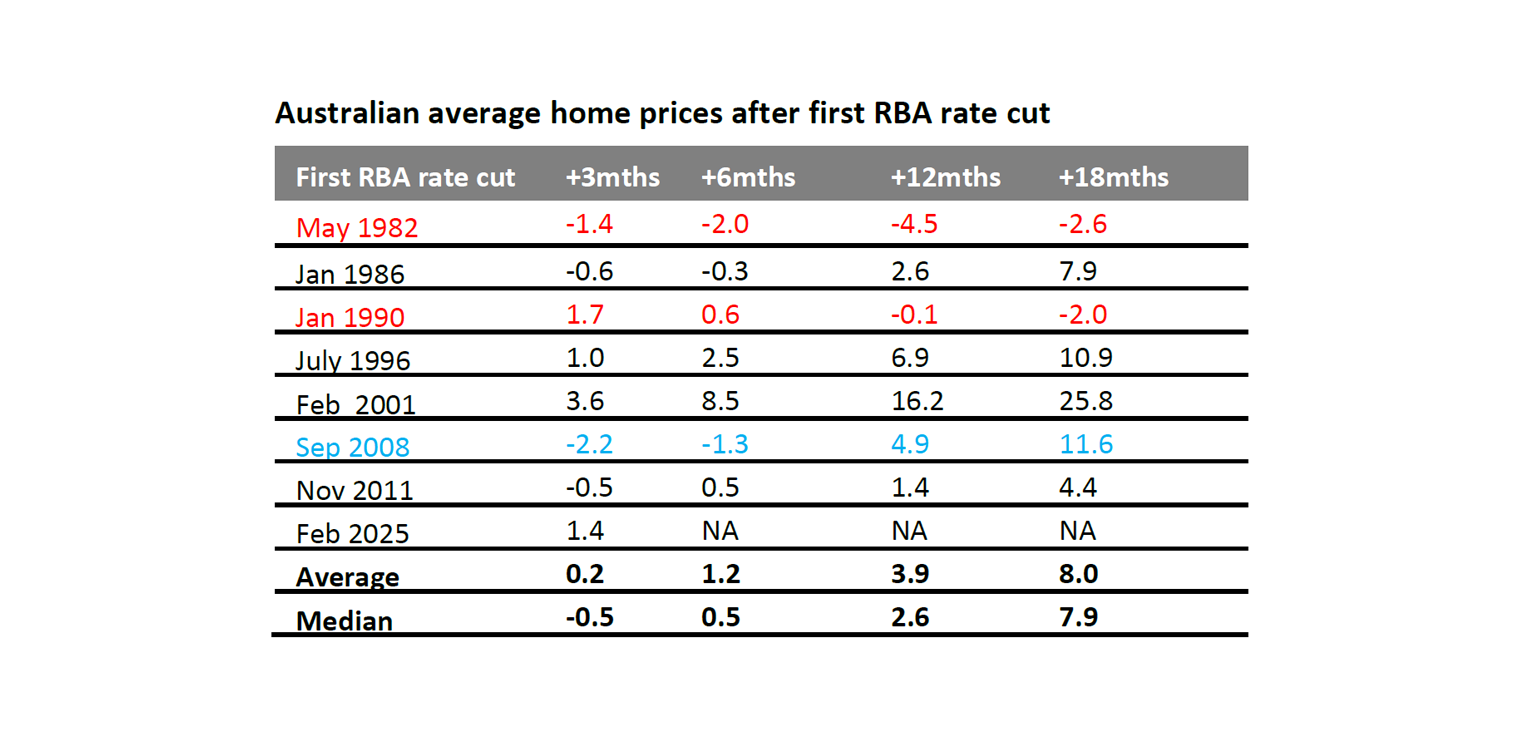 Cotality. Australian recessions are in red. The GFC is in blue. Source: RBA, Cotality, AMP
Third – Australian housing is chronically undersupplied
This has been the case since the mid-2000s, when immigration levels and hence population growth, surged and the supply of new homes did not keep up. The accumulated housing shortfall is around 200,000 dwellings at least and possibly 300,000, depending on household size assumptions. The economic reality is that when underlying population-driven demand for housing exceeds its supply, prices rise, and that is what we have been seeing for the last twenty years. The capital gains tax discount, negative gearin,g and foreign demand may have played a role, but they have been a sideshow to this demand and supply imbalance.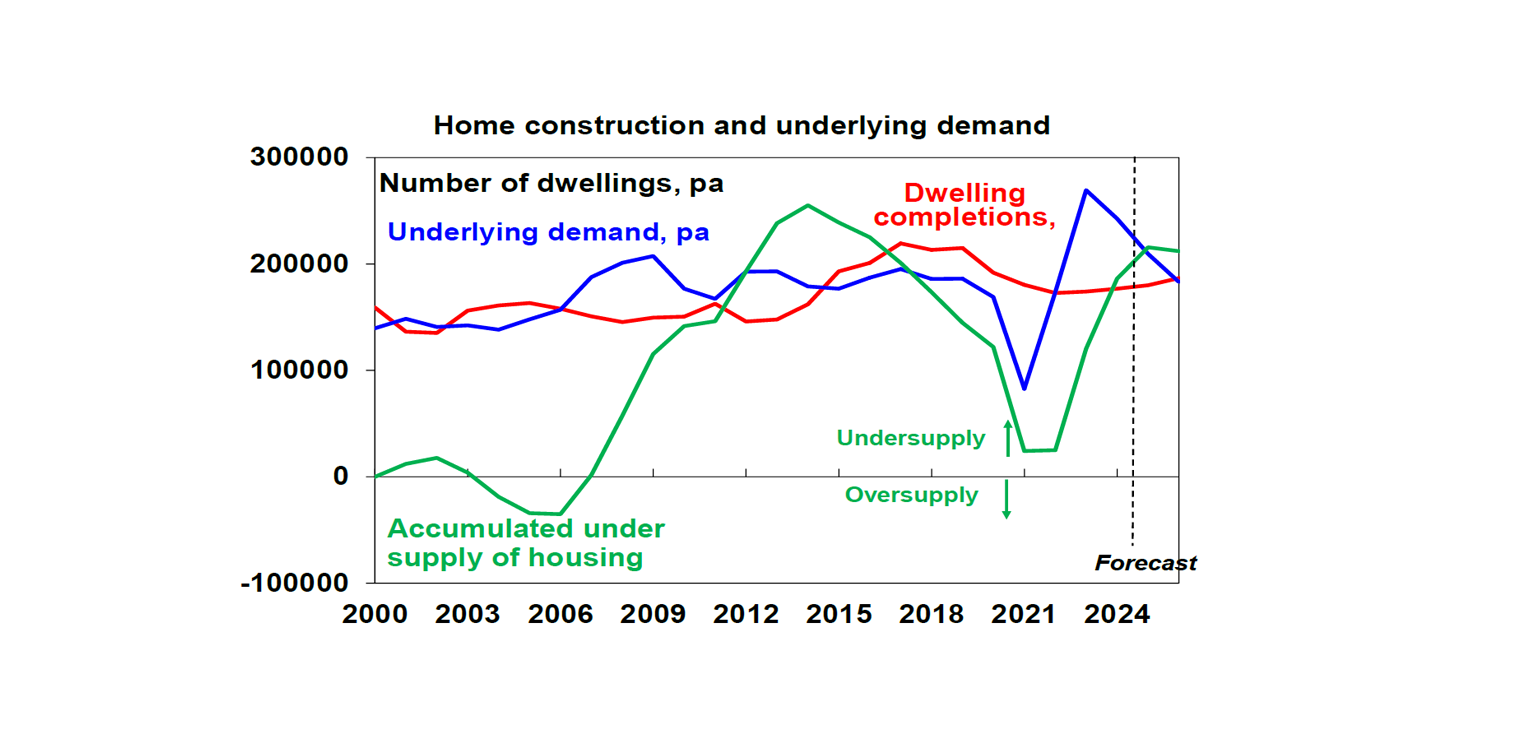 Source: ABS, AMP
Fourth – home building completion times have surged
Part of the solution is to slow immigration growth to levels more in line with the ability of the housing industry to supply homes. Immigration has been falling lately. But it’s also about boosting supply, and if we want to reduce the accumulated undersuppl,y it’s critically important that Federal and state governments retain the Housing Accord commitment to build 240,000 dwellings a year, compared to around 180,000 over the last year. Over the last decade, the time taken to build a house from approval has risen by 57% and that for units by 65% reflecting increasing regulations, rising costs, labour shortages, etc. To meet the Housing Accord target, we need deregulation, more homebuilders, a greater focus on units and more ways to lower costs.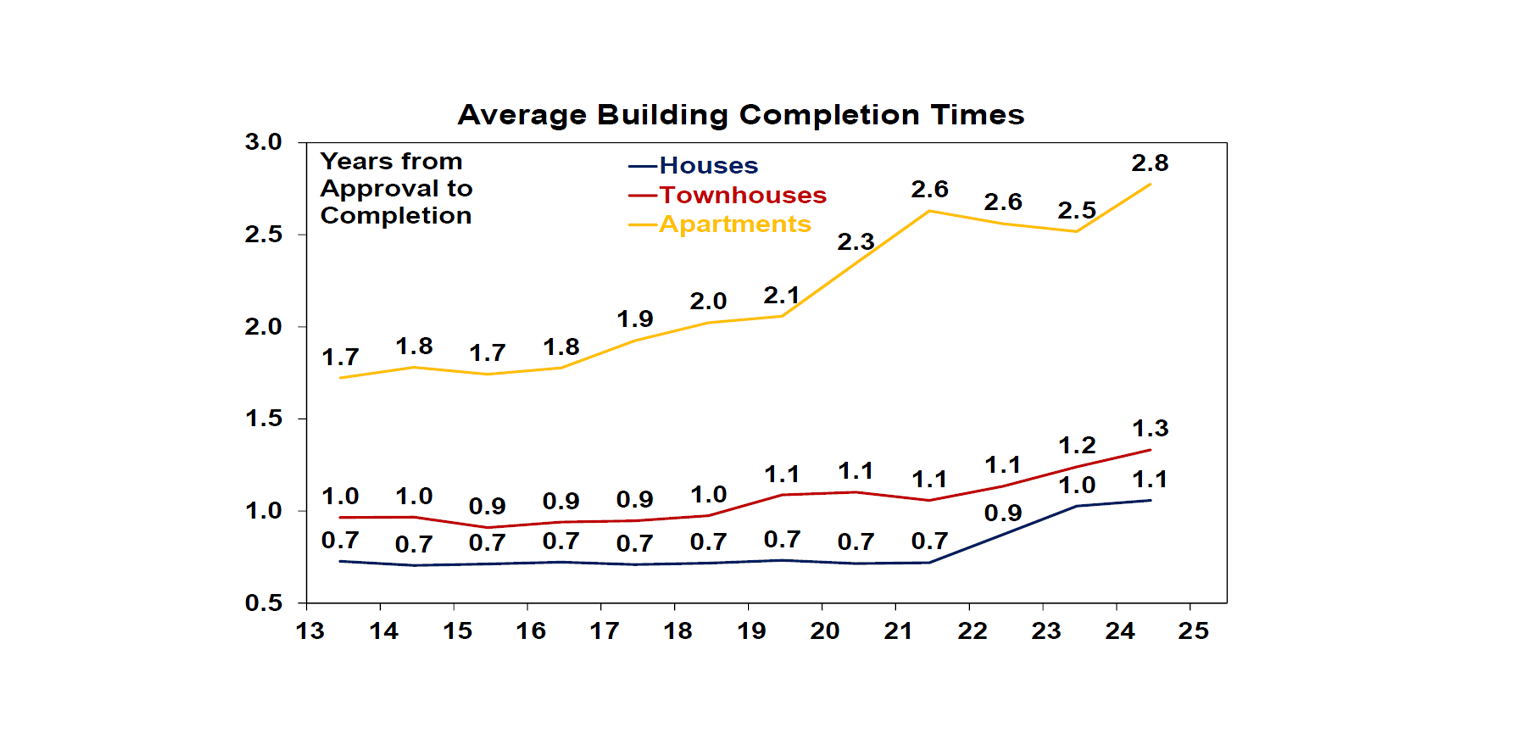 Source: ABS, AMP
Fifth – Australian housing is very expensive
Chronically deteriorating housing affordability in Australia has been evident since the 1990s. It’s evident in rising home price to wage and income ratios, the rise in years taken for an average earner to save a 20% deposit from around 4 years 40 years ago to around 10 now, and the ratio of home prices to rents being around 30% above its long-term average. The expensive nature of Australian property and the high level of debt that goes with it leaves the economy vulnerable should high interest rates or unemployment make it harder to service loans and is leading to rising wealth inequality. In the near term though, it may constrain the extent of the upswing in property prices through this cycle.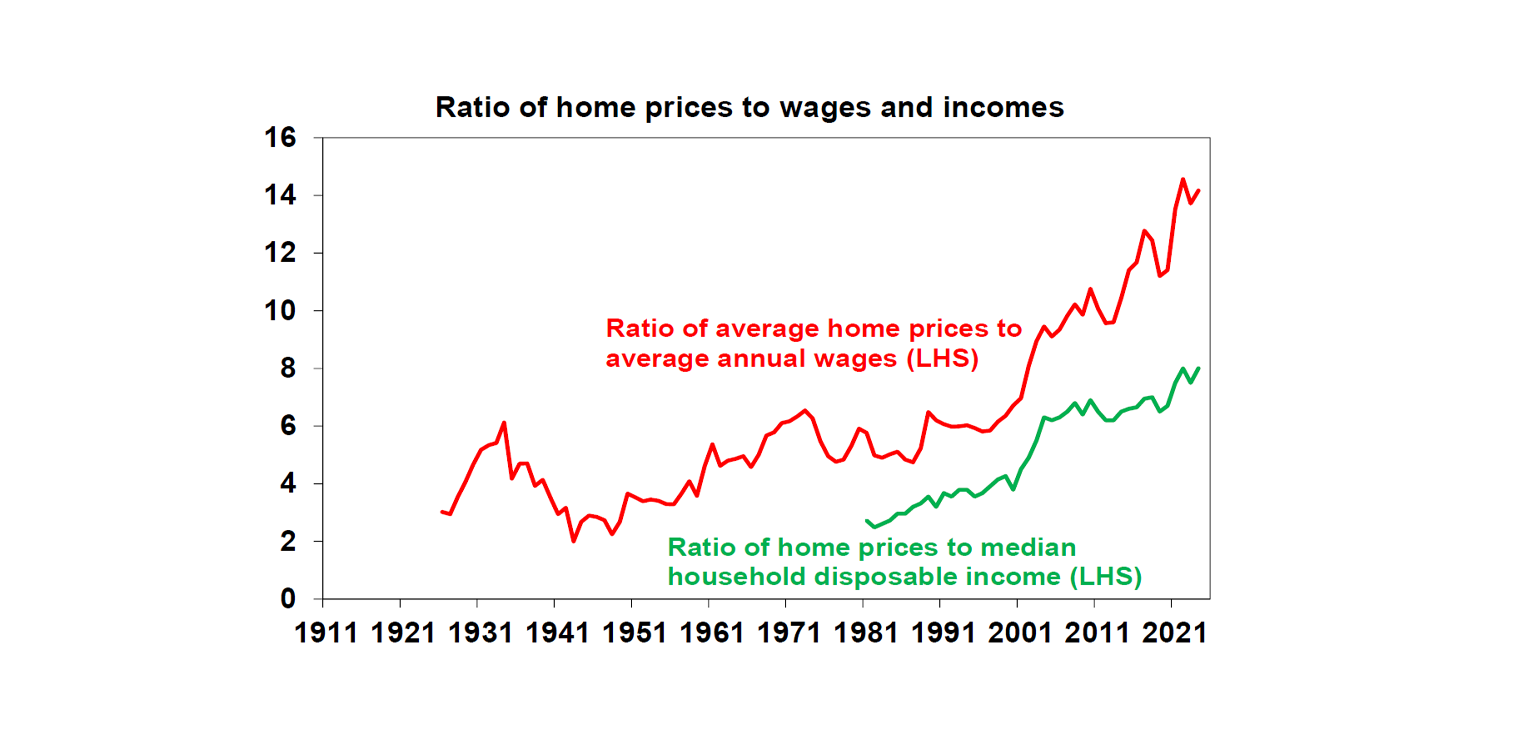 Source: ABS, Cotality, AMP
Sixth – it’s also very diverse
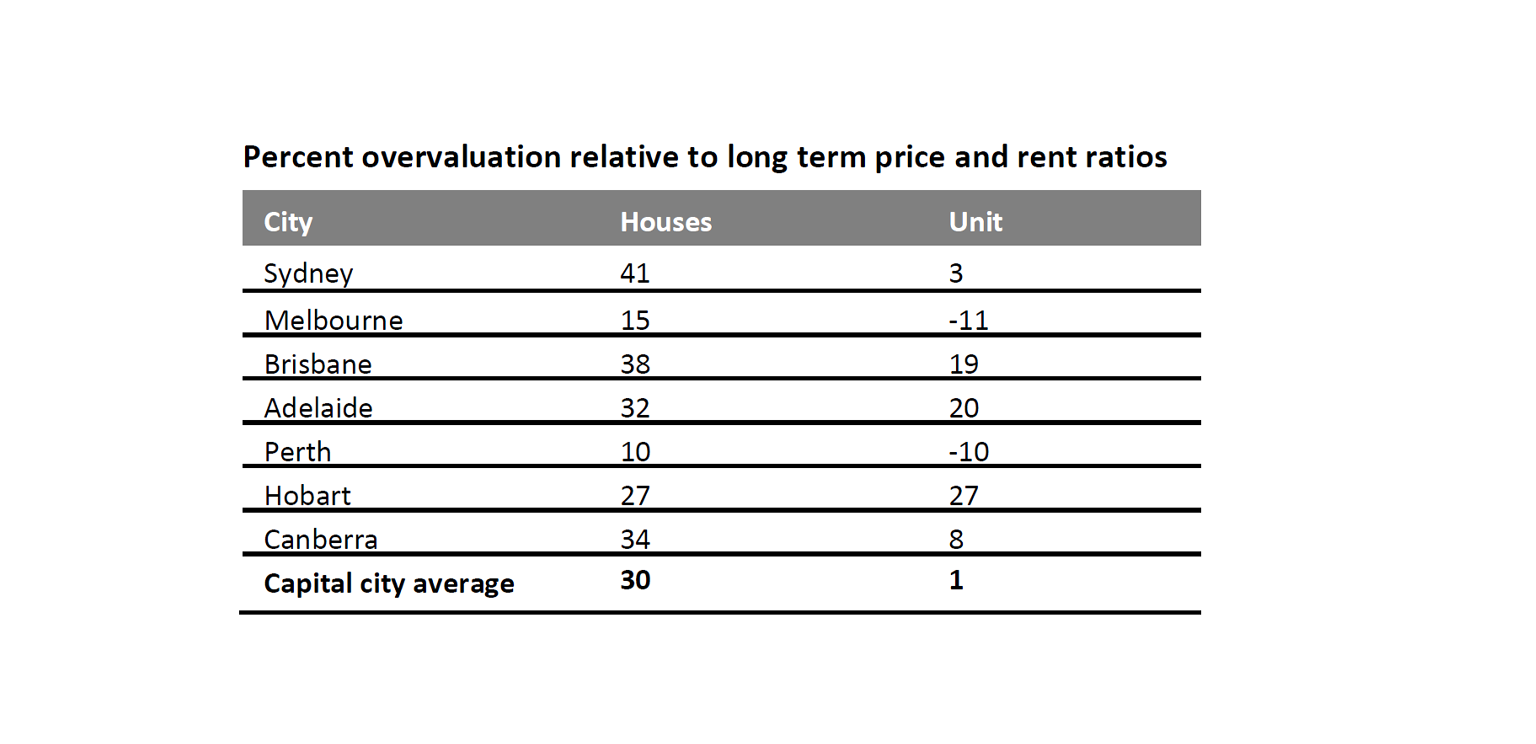
While we often refer to “the Australian property market”, in reality there is significant divergence between localities resulting in diverse cycles. The divergence is reflected in measures of valuation. On this basis while houses are 30% overvalued, units are only 1% overvalued. Perth and Melbourne stand out as the least overvalued markets in terms of houses and both are actually undervalued in terms of units.
 Source: REIA, AMP
Finally – mortgage arrears are still low
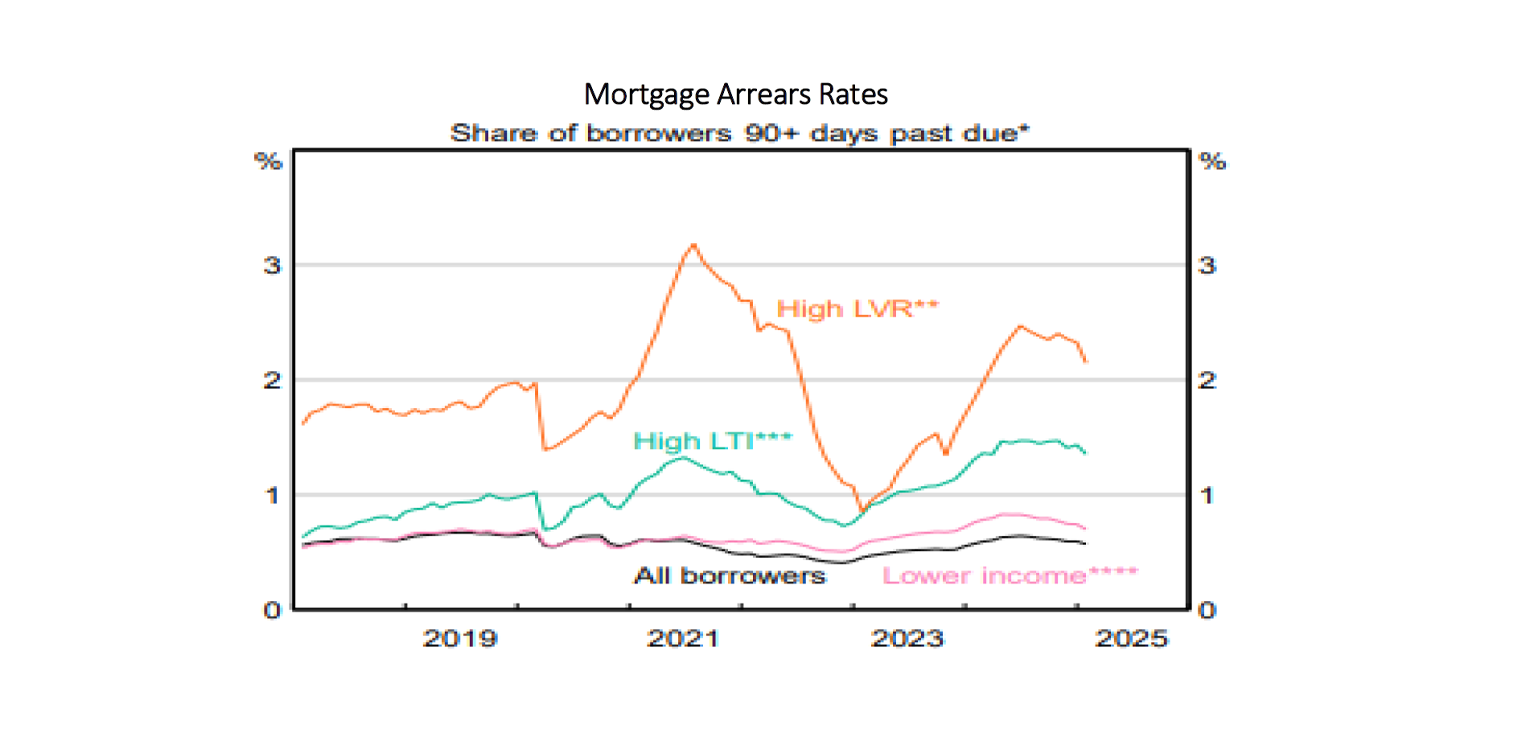
Reports of mortgage stress have been common for the last two decades. There is no denying housing affordability is poor, debt is high, and many households are still suffering significant mortgage stress. But despite this mortgage arrears rates remain remarkably low at less than 1% on average which leaves them low in international comparisons too. They are higher for those with high loan-to-value ratios and high loan to income ratios but even here they are still low and have been falling lately. The low level of arrears partly reflects strong lending standards in Australia combined with the strong jobs market and a high level of savings buffers coming out of the pandemic. So absent a shock, like much higher unemployment, don’t expect an avalanche of distress listings.
Source: RBA Financial Stability Review, April 2025
Where to now?
Forecasting property prices is fraught. But the base case is for property prices to rise 5 to 6% this year driven by rate cuts and the chronic housing shortage but with poor affordability constraining the upswing. The main downside risk is that rising unemployment and a delay in rate cuts depresses buyer demand, but the main upside risk is that another bout of FOMO takes hold as rates fall. The key for savvy investors is to look for properties offering decent rental yields.
Source: Written by Shane Oliver, Head of Investment Strategy and Economics and Chief Economist, AMP Capital, 22 July 2025


